Why You Should Avoid Car Title Loans Unless It Is Your Absolute Last Resort
Sponsored Ads
auctmarts.com
Our Top ChoiceFree Shipping On All Orders
- Motorcycle Fairings
- Windshields
- Fairing Bolts
- Tank Pads
- Heat Shields
- Seat Cowls
Online retailer specializing in aftermarket motorcycle fairings, bodywork, and related accessories for sportbikes.
fenrir-moto.com
- Bar End Mirrors
- Side Mirrors
- Handlebar Mirrors
- Emark Mirrors
- Motorcycle Accessories
Sells motorcycle bar end mirrors and side mirrors for various bike brands and models.
ibuture.com
Up To 77% Off, BOGO Offers, And Free Shipping!
- Cordless Vacuum Cleaners
- Portable Car Jump Starters
- Stick Vacuums
- Vacuum Accessories
- Smart Tire Inflators
Sells high-performance cordless vacuum cleaners and portable car jump starters for modern homes and vehicles.
What is a car title loan?
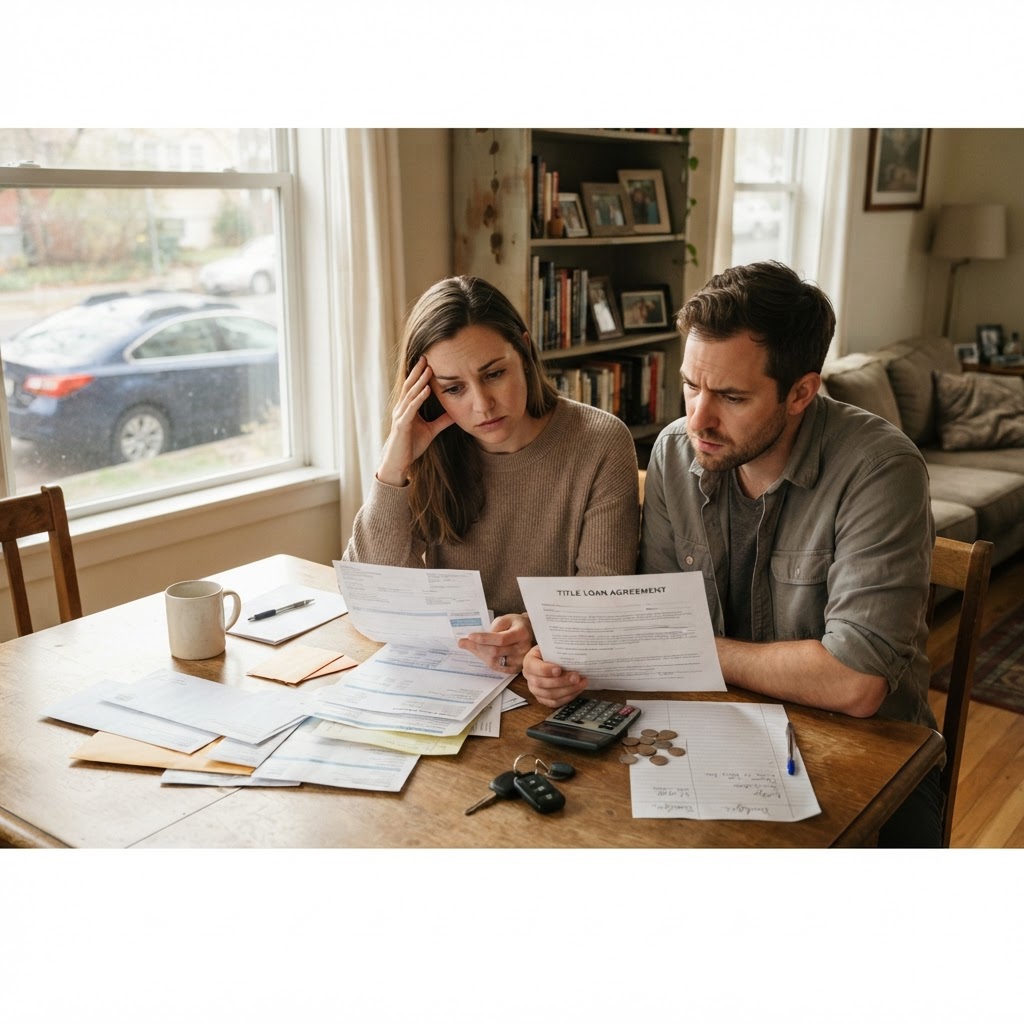
A car title loan is usually a short term loan that a borrower takes against the value of a vehicle that they own. A vehicle must be 100% owned for a car title loan, and you must provide the car title document as proof of ownership to qualify for a loan. Car title loan lenders generally rely on people who need cash very quickly.
Are they a good idea?
Car title loans should be viewed only as a last resort because a car title loan is arguably the most expensive credit available in America today. Consider that the cost of borrowing money through a car title loan can be as high as an APR of 300% (and if not that high it is usually at least 3 digits). In comparison even the most expensive credit card APR will run at 25%. APR is the annual percentage rate that you pay for the credit that you have with your lender. The interest rate that you are paying as well as their administrative costs are covered under the APR.
How does a car title loan work?
If you have no other option but to take a car title loan, your lender will put a lien on your vehicle until you loan or debt is paid. If you sell your car when there is a lien on it, the lender will be repaid your debt before you receive the balance of the amount the car sells for. If you are unable to make you car title loan payments your lender can repossess your vehicle - so timely payment of the loan is a must.
Why do people take car title loans?
Car title loans are the quickest way to take a loan in America today. Since you are putting your car up as security or collateral, no credit checks are required. It is a speedy if very expensive way of taking a short-term loan.
Apart from the very high-cost of these loans are there any other downsides I should be aware of?
Really unscrupulous lenders may ask you to purchase add-ons at the time you take your loan. The kind of add-on that they insist you purchase are products like roadside assistance. The ‘cost’ of these add-on products are usually added to the total loan that a borrower will take and can add a crazy amount to the loan that needs to be repaid. If you are being forced to take an add-on product we would strongly suggest you find an alternate lender. Though car title loans are available for periods of up to 3 years, a loan of this kind should not be considered for anything longer than 2 weeks to a month.
Related Sales Tips
Stop Losing Money By Choosing The Wrong Checking Account For Your Needs
A checking account is a necessity for anyone looking to put their money in a safer place than under the mattress. It also offers up a whole new world of financial convenience. Checking accounts are simply a place to stor...
Nov 6, 2026
Stop Overpaying For Small Business Loans By Avoiding These Hidden Traps
The U.S. has nearly 27 million small businesses and around 80% of them use some form of credit to finance their operations, including bank loans and credit cards. Risk These lines of credit can be vital to keep small bus...
Nov 3, 2026
Stop Overpaying For Wheel Alignment With These Secret Discount Coupons
Ensuring that your wheels are properly aligned can help avoid problems such as irregular tire wear, poor handling or a crooked steering wheel. It also increases gas mileage. It should be done annually, if your car is sta...
Oct 29, 2026
About the Author
Emily Williamson
Emily Williamson is a personal finance expert dedicated to helping readers find genuine savings and smart shopping strategies. With years of experience in consumer finance, Emily combines practical advice with trusted insights to guide you toward smarter financial decisions.